Capital One’s car-buying agent brings banking AI to the dealership handoff
Capital One describes vehicle comparison and appointment actions; the article examines the dealer handoff and buyer understanding.
A customer who wants to see a car on Saturday is asking for an appointment, not a lecture about artificial intelligence. That makes vehicle shopping a revealing place to examine the latest banking technology. An assistant must understand the request, find relevant stock and pass something useful to a dealer. A beautifully written answer that leaves the appointment unmade has not completed the customer's task.
Capital One described a real move into that territory on 5 March 2025. Its [technical account of Chat Concierge](https://www.capitalone.com/tech/ai/future-of-ai-car-dealerships-shopping/) says the proprietary, multi-agent assistant can compare vehicles and arrange appointments through participating dealer websites. It describes a workflow that plans actions, checks them and explains them to the buyer. This is a bank's account of its own deployed product, checked for this article on 16 October 2026; it is not an independent evaluation of customer welfare.
From answering a question to carrying out an instruction
There is a practical difference between answering whether a model comes with heated seats and asking a salesperson to reserve a test drive. The first task depends on finding correct information. The second changes another person's working day. It may create a sales lead, expose contact information or occupy a scarce appointment. The service therefore needs a clear moment at which browsing becomes an instruction.
Capital One's March explanation says Chat Concierge uses a customised Llama-based model and works with dealer customer-management systems, including support for Capital One and non-Capital One products. Its description includes confirming the vehicle, checking an action plan and simulating whether that plan follows business rules. Those are specific reported capabilities. They do not establish that the assistant approves a loan, guarantees stock availability or can negotiate a binding purchase on a customer's behalf. [Product account](https://www.capitalone.com/tech/ai/future-of-ai-car-dealerships-shopping/).
For a buyer, the appealing part is continuity. A person can ask about a vehicle and move toward a visit without starting the conversation again elsewhere. For the dealer, a structured request could be easier to follow than an abandoned chat transcript. Whether either benefit occurs depends on the handoff: which vehicle was discussed, what the person actually requested and whether a member of staff can correct the record.
The possibility of action also changes what counts as a mistake. A wrong answer can mislead. A wrong appointment can additionally trigger reminders and follow-up calls. A stale inventory record might send a buyer across town for a vehicle that has already been sold. These are operational possibilities to test, not failures documented at Capital One. They explain why action-taking assistants need evaluation beyond conversational fluency.
A bank product inside a wider shopping process
The initiative sits alongside other bank-built tools rather than representing every use of AI at the company. In a [24 June 2025 technology article](https://www.capitalone.com/tech/ai/innovating-financial-services-through-customer-centered-ai/), Capital One lists Chat Concierge with products including Auto Navigator and AirKey. It presents the work as part of a longer investment in data, research and customer technology. The list establishes that these are distinct products; it should not be read as evidence that every function shares one model or one customer permission.
That distinction matters when banking and retail meet. Comparing cars, requesting contact, checking financing eligibility and applying for credit are different steps. A useful service should tell people which step they are taking. An appointment confirmation ought not to resemble approval for a financial product. Equally, a financing discussion should not quietly become consent to receive unrelated marketing. The implementation question is how the interface preserves those differences as the conversation moves.
Dealer staff also need an understandable record. A short summary might say a person prefers a particular body style and would like a visit after work. It should distinguish those preferences from conditions the dealership has accepted. Staff need to see unresolved questions, not merely a model's polished account. That creates work in reviewing requests, maintaining inventory and handling exceptions; it does not support a prediction that sales or banking jobs will disappear.
What the public record can and cannot tell a buyer
The product descriptions explain intended functionality and development choices. They do not provide an independently reproducible test set, a complete account of unsuccessful appointments or customer outcomes by language and accessibility need. This article therefore does not repeat conversion comparisons as proof of better financial outcomes. A completed sale can be useful to a dealer while still leaving open whether the buyer understood the terms or obtained a suitable product.
There is an established way to organise those questions without pretending a framework certifies the product. [NIST's AI Risk Management Framework](https://www.nist.gov/itl/ai-risk-management-framework) is voluntary, and its public page says version 1.0 is being revised. Its usefulness here is as a way of organising responsibility and evaluation, not as a bank-specific rule or evidence that NIST has endorsed Chat Concierge.
The [NIST generative-AI profile published on 26 July 2024](https://www.nist.gov/publications/artificial-intelligence-risk-management-framework-generative-artificial-intelligence) is a cross-sector companion to that framework. It helps place generative systems within a broader assessment of trustworthiness. Neither publication can answer whether a particular dealer's inventory feed is current. The bank, dealer and technology team still have to establish that through their actual service records and tests.
A proposed learning exercise: the appointment that must not multiply
The following is an original training proposal, not a description of Capital One's internal testing. A bank and an invented dealership could rehearse a car-shopping conversation using synthetic vehicles and contacts. The learner asks about a family car, changes the preferred time and then loses connectivity after confirming an appointment. No real customer, credit application or live dealership system is involved.
The exercise starts with an ordinary inventory question. The assistant should identify the source and freshness of the relevant stock record. Next, the learner requests a visit but gives an ambiguous time: Saturday afternoon. A successful rehearsal asks for enough detail to create a useful request. It does not fill the gap by inventing an appointment or claiming that the dealer has confirmed something the dealer has not accepted.
Then comes the interruption. The learner sees no confirmation and presses the button again. The team inspects whether the system creates one request, two requests or an uncertain state that needs checking. It also tests a sold vehicle, an unavailable salesperson and a request to cancel. The important measure is whether staff and buyer can reconcile the same action, rather than whether the assistant can produce another reassuring sentence.
Finally, a human reviews the language around financing. The assistant must preserve the difference between shopping, prequalification and an application in the exercise's chosen scope. It should give a clear way to speak with the dealer or bank when the conversation reaches an unsupported step. Learners record omissions and misleading implications separately from appointment completion, because a fast handoff can still be a confusing one.
Capital One's reported deployment makes this more than an abstract agent demonstration. It places action-taking technology in a familiar consumer journey with several responsible parties. The lesson for banking teams is specific: when an assistant crosses from conversation into another organisation's workflow, the quality of the shared instruction becomes part of the product. Customers need to know what happened, who has received their request and what remains undecided.
Explanatory diagram and accessible reading guide
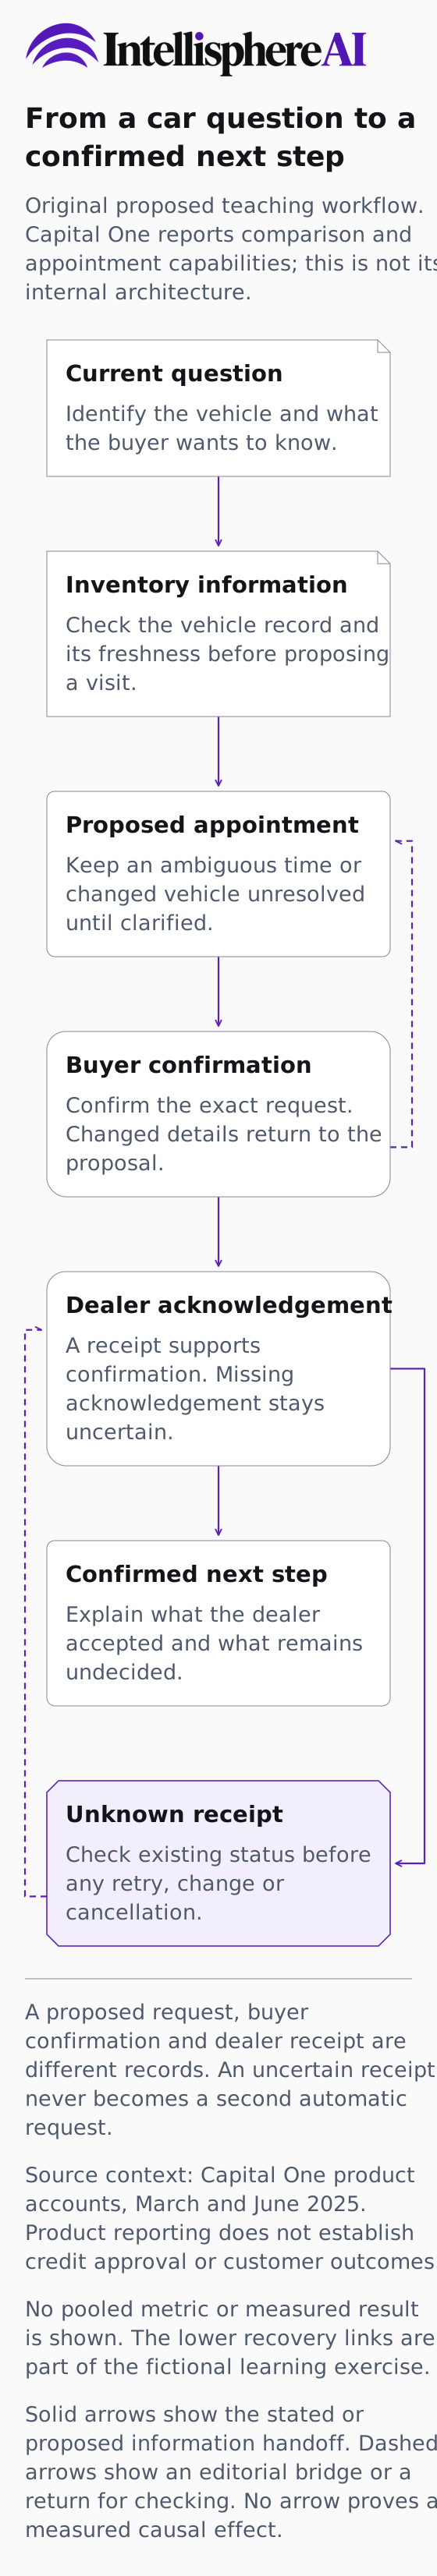
*Original educational infographic based on attributed reports and a fictional proposed exercise; not the named bank’s internal architecture, actual customer decision or measured result.*
[Open the full-size explanatory diagram](/assets/bank-us-appointment-boundary-20261016.svg)
This original diagram explains attributed source context and a fictional learning exercise. The exercise has not been run; the diagram is not an authentic product interface, internal bank architecture or measured operational result.
From a car question to a confirmed next step
Original proposed teaching workflow. Capital One reports comparison and appointment capabilities; this is not its internal architecture.
Current question
Identify the vehicle and what the buyer wants to know.
Inventory information
Check the vehicle record and its freshness before proposing a visit.
Proposed appointment
Keep an ambiguous time or changed vehicle unresolved until clarified.
Buyer confirmation
Confirm the exact request. Changed details return to the proposal.
Dealer acknowledgement
A receipt supports confirmation. Missing acknowledgement stays uncertain.
Confirmed next step
Explain what the dealer accepted and what remains undecided.
Unknown receipt
Check existing status before any retry, change or cancellation.
A proposed request, buyer confirmation and dealer receipt are different records. An uncertain receipt never becomes a second automatic request.
Source context: Capital One product accounts, March and June 2025. Product reporting does not establish credit approval or customer outcomes.
No pooled metric or measured result is shown. The lower recovery links are part of the fictional learning exercise.
Solid arrows show the stated or proposed information handoff. Dashed arrows show an editorial bridge or a return for checking. No arrow proves a measured causal effect.
The buyer question determines which inventory information is relevant.
Checked information supports a proposed visit, not a guaranteed booking.
The buyer reviews the specific proposed request.
A confirmed request is sent for dealer acknowledgement.
Changed details return to the proposal for review.
A verified dealer receipt supports an explained next step.
A missing receipt enters an explicit uncertain state.
Check existing status before deciding whether another action is needed.
Diagram source references
- [S15: AI for Car Dealerships: Smarter Car Shopping | Capital One](https://www.capitalone.com/tech/ai/future-of-ai-car-dealerships-shopping/) — Capital One.
- [S16: Shaping Financial Services with Patented AI | Capital One](https://www.capitalone.com/tech/ai/innovating-financial-services-through-customer-centered-ai/) — Capital One.
- [S26: AI Risk Management Framework | NIST](https://www.nist.gov/itl/ai-risk-management-framework) — NIST.
- [S27: Artificial Intelligence Risk Management Framework: Generative Artificial Intelligence Profile | NIST](https://www.nist.gov/publications/artificial-intelligence-risk-management-framework-generative-artificial-intelligence) — NIST.